
Is Hive5 safe to invest in? This guide explains how the marketplace works, its legal status and the risks, so you can decide for yourself. It isn’t investment, legal or tax advice.
Short answer: is Hive5 safe to invest in? No investment is risk-free, and that includes Hive5. Hive5 is a loan investment marketplace: from €10, you buy claim rights on loans that lending companies have already issued, and you choose them yourself or through Auto Invest. If a payment is more than 60 days late, the lending company named in your Investment Agreement must buy your claim back, but the buyback depends on the lending company’s ability to pay. You can also offer investments for sale on our Secondary Market before they mature. Our agreements, legal summaries and group accounts are public, so you can read the terms before you invest. Hive5 can suit a small part of a diversified portfolio if you accept the risks. Capital at risk: you can lose some or all of the money you invest.
In this guide: Is Hive5 safe? · How it works · Who runs Hive5 · Legal status · Buyback and safeguards · Risks · Reviews · Pros and cons · Who it may suit · Check it yourself · FAQ · Conclusion
So, is Hive5 safe to invest in?
The answer depends on how much risk you can carry, because no investment on Hive5 is free of risk. What you can check is how the marketplace works, what stands behind each investment and where its limits are.
Start with the basics. Hive5 marketplace d.o.o. za usluge, a registered company in Zagreb, Croatia, runs Hive5 and has operated the marketplace since July 2022 (About us). Unlike a bank, Hive5 doesn’t lend money itself. Instead, it lists claims on loans that lending companies in Romania, Poland and Spain have already issued, and you buy the right to the repayments.
Two features sit around each investment: the 60-day buyback obligation and a separate account for money you haven’t invested yet. However, both have limits. For example, the buyback depends on the lending company’s ability to pay, and every lending company belongs to the same group as Hive5. Your investments also aren’t bank deposits, so no deposit guarantee or investor compensation scheme covers them.
How investing on Hive5 works
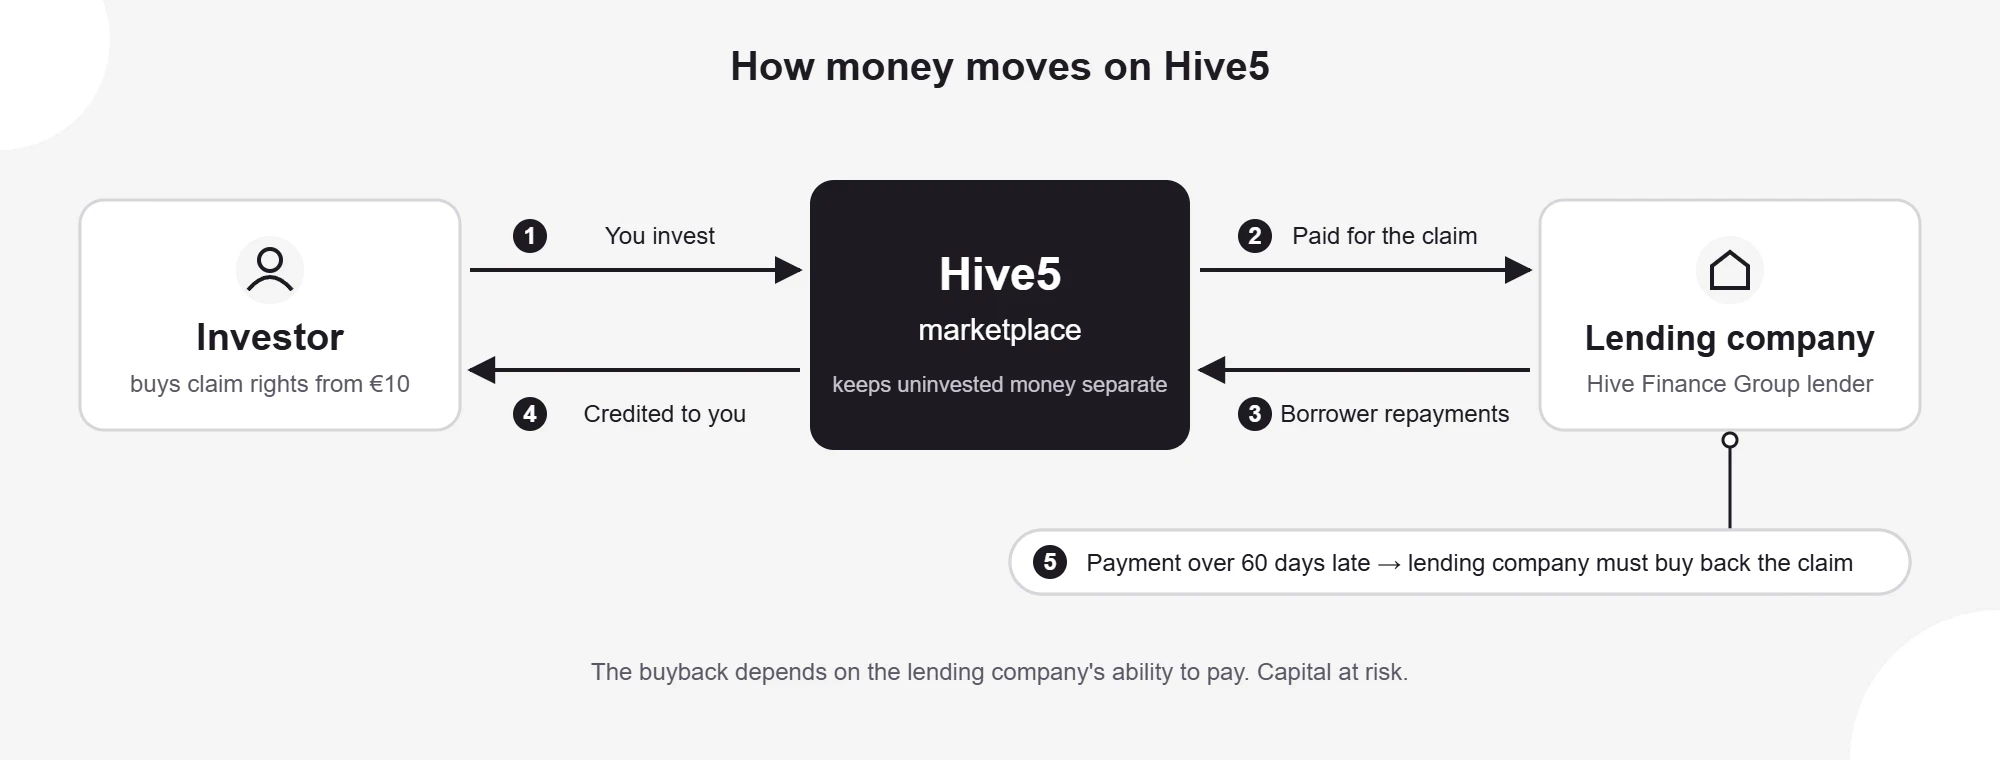
When you invest on Hive5, you don’t lend money directly to a borrower. Instead, you acquire claim rights to a loan that a lending company (loan originator) has already issued, under an Investment Agreement that names the borrower, the lending company and the payment terms. Our page on how investing on Hive5 works walks through each step.
What you buy
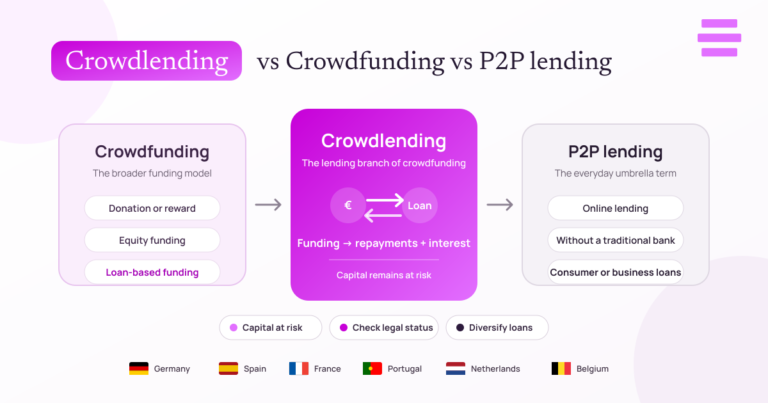
Hive5 is often grouped with P2P lending platforms, but it works differently. A lending company issues and funds a loan, the claim appears on our marketplace, and you buy claim rights: the contractual right to repayments under an Investment Agreement. You can read the Investment Agreement template before you invest.
You can start from €10. Then you can pick investments yourself or set up Auto Invest, which invests your money by the rules you set (help centre). If you want to exit before a loan ends, you can offer eligible investments for sale on our Secondary Market. A sale depends on another investor buying, so it isn’t certain. If no buyer comes forward, the investment stays in your portfolio until it’s repaid.
We run the marketplace and process the payments. In return, the lending companies pay us service fees (Transparency Hub). Any fees for investors follow the Price List on our website (User Agreement).
Who issues the loans
Every lending company on Hive5 belongs to Hive Finance Group, the group that also owns Hive5. At the moment, three of them list investments, and each one has a profile on our loan originators page:
| Lending company | Country | What it lends | Regulatory position, as stated on our lender page |
|---|---|---|---|
| Credilink | Romania | Revolving credit lines for consumers | Registered with the National Bank of Romania as a non-bank financial institution |
| Firmeo (Firmeo Business Finance sp. z o.o.) | Poland | Instalment loans to entrepreneurs and small businesses | Business-only lender, so it doesn’t need a consumer-lending registration with the Polish regulator (KNF) |
| FinJet (Nectar Capital S.L.) | Spain | Mainly short-term consumer loans | Non-bank consumer lender, not supervised by the Bank of Spain |
For some offers, the lending company is itself the borrower. For example, our Transparency Hub describes Credilink investments as “linked to business financing provided to Credilink”, and Firmeo’s first offer, in October 2025, funded Firmeo’s own business needs (Hive5 blog). So check your Investment Agreement before you invest, because it names both the borrower and the company that owes the buyback.
Our group’s fourth lending business, Ekspres Pożyczka in Poland, stopped listing loans on Hive5 in March 2025 because it could fund itself (Hive5 blog). Because every lender belongs to the same group, spreading your money across them doesn’t spread it across unrelated companies, and difficulties can affect several companies at once. Our guide to concentration risk shows how that affects a loan portfolio.
What Hive5 is not
Hive5 isn’t a bank or deposit-taking institution, a payment or e-money institution, a crowdfunding platform for project financing, or an investment adviser or portfolio manager (About us).
Who runs and owns Hive5
Hive Finance Group owns Hive5. At the end of 2024, Hive Finance UAB, the Vilnius parent of the group, owned all of Hive5 (2024 audited report, note 1). In October 2025 we announced that co-founder Andrius Rupšys owned 65% of Hive Finance and Ruptela Group the other 35% (Hive5 blog, 17 October 2025). Later, when the group named Krisjanis Znotins Group CEO in May 2026, we said he was becoming a minority shareholder (Hive5 blog, 5 May 2026). We haven’t published the shareholding split since then.
Artis Pukitis became CEO of Hive5 in October 2026, and Zigmars Lacis joined as Group CFO the same month. Group Chief Risk Officer Alexander James, Group COO Anete Pallo and our Head of Operations Inga Zubanovė complete the team named on our Transparency Hub and leadership page.
By the end of October 2026, investors had funded loans worth €239.7 million through Hive5, and 30,521 investors had registered (October 2026 platform update, published 5 November 2026). However, these are our own figures, and no auditor has checked them.
Is Hive5 regulated or licensed?
Hive5 does not operate under a financial services licence (help centre). Based on our current legal assessment, made with our legal advisers in Croatia, Hive5’s model does not require authorisation as an ECSP crowdfunding service provider, MiFID investment firm, payment institution or e-money institution (legal statement, 5 July 2026). That’s our own assessment, and we haven’t published any regulator’s view on it.
The 2024 legal opinions
First, in January 2024 we published the conclusion of a Croatian law firm and said a Lithuanian law firm agreed (Hive5 blog, 23 January 2024). The Croatian firm, Divjak, Topić, Bahtijarević & Krka, assessed our business under Croatian law, including the Capital Markets Act, the Credit Institutions Act, the Consumer Credit Act and the Factoring Act. Its opinion of 23 January 2024 found that, at that time, we didn’t need a licence or supervisory approval from the Croatian authorities. However, we’ve published a summary, not the full opinion.
This follows from how our model works. Hive5 doesn’t take deposits, grant loans or arrange new lending. Instead, it lists claims on loans that lending companies have already issued, and investors buy them.
The 2026 e-money advice
Later, Babić & Partners advised us on 1 June 2026 under Croatia’s Electronic Money Act and Payment Services Act. As our summary on the Transparency Hub explains, we hold user funds in a bank account and pass them to lending companies without issuing electronic money, so the model the lawyers reviewed doesn’t need an e-money licence.
The EU crowdfunding rules
The EU’s crowdfunding regulation, Regulation (EU) 2020/1503, covers platforms that match investors with businesses seeking new funding, including by facilitating loans. Providers need authorisation from their national regulator, and ESMA keeps a public register of them. On our current legal assessment, this regime doesn’t apply to Hive5’s model, because investors buy claims on loans that lending companies have already issued (legal statement).
What this means for you
Because Hive5 doesn’t operate under a financial services licence, your investments sit outside the investor protection rules that come with licensed investment products. Instead, you rely on the Investment Agreement, the lending company and the features described below.
Is Hive5 licensed in Germany, Spain, France, Portugal, the Netherlands or Belgium?
No. We hold no licence in any of these six countries, because our legal position rests on Croatian law, where Hive5 is established. Our help centre also lists who can invest and the countries we restrict.
Before you invest, you can check each country’s financial regulators for licences and investor warnings. IOSCO’s I-SCAN also searches many regulators’ warning lists at once.
| Country | Financial regulators |
|---|---|
| Croatia (Hive5’s home country) | HANFA and Croatian National Bank |
| Germany | BaFin |
| Spain | CNMV and Bank of Spain |
| France | AMF and ACPR |
| Portugal | CMVM and Bank of Portugal |
| Netherlands | AFM and De Nederlandsche Bank |
| Belgium | FSMA and National Bank of Belgium |
Your country’s deposit guarantee and investor compensation schemes don’t cover Hive5 investments. Also, the agreements choose Croatian law and Croatian courts (Investment Agreement 17.10; User Agreement 15.2).
What stands behind your investment, and what doesn’t
Hive5 investments come with a 60-day buyback obligation and a separate account for uninvested money. Neither is a state-backed guarantee, and both depend on someone else being able to pay.
The 60-day buyback obligation
If a payment is more than 60 calendar days overdue, the lending company named in your Investment Agreement is contractually required to buy back your claim rights, with accrued interest. This is the lending company’s obligation, not Hive5’s, and it depends on that company’s ability to pay. It is not a guarantee.
The same applies if insolvency proceedings start against the borrower (Investment Agreement, 13.1), and the buyback price covers interest for no more than 60 days of delay (13.7). The process runs automatically, so you don’t need to do anything (help centre). Our help centre also explains what happens when a repayment is late.
Because every lending company belongs to Hive Finance Group, a problem across the group could affect several lenders at once. The agreements don’t set up a reserve fund or insurance for the buyback. And if a lending company failed, we could take over managing its claims but not its buyback obligation (Investment Agreement 8.1.8).
Money you haven’t invested
Money you transfer to Hive5 and haven’t invested is held in a separate account from Hive5’s own funds. It earns no interest, it isn’t a bank deposit, and no deposit guarantee scheme covers it (User Agreement, 4.10, 4.11 and 4.14).
In legal terms, your balance is a claim against Hive5 for that amount. The separation doesn’t remove bank, operational or insolvency risk (Transparency Hub). Money can also wait uninvested for a while, for example when no investment matches your Auto Invest settings (help centre).
If Hive5 or a lending company became insolvent
If Hive5 became insolvent, existing investments would still follow their agreements. We would give investors information on their transactions, stop concluding new Investment Agreements and return available funds as the agreements and the law allow (help centre). Even so, servicing and repayments could stop for a time, and you might recover only part of your money (Transparency Hub).
If a lending company became insolvent, the procedure in the Investment Agreement would apply, and that could reduce its ability to pay, including the buyback (help centre).
What no scheme covers
Hive5 investments aren’t bank deposits. No deposit guarantee scheme or investor compensation scheme covers them (help centre).
The main risks of investing on Hive5
Our help centre names seven key risks (help centre). This table shows what each one means, what reduces it and what risk you still carry. For the risks of loan-based investing in general, see our guide to P2P lending risks.
| Risk | What it means | What reduces it | What remains |
|---|---|---|---|
| Borrower credit risk | Borrowers pay late or not at all | The lender’s credit checks and the 60-day buyback | Losses if the buyback isn’t paid |
| Lending company risk | A lending company can’t meet its obligations | Audited group accounts you can read | Every lender is in the same group |
| Buyback risk | The buyback is late or not paid | An automatic process under the Investment Agreement | It’s a contractual obligation, not state-backed |
| Liquidity risk | You can’t exit before the loan ends when you want to | Offering investments for sale on our Secondary Market | A sale needs a buyer, may need a discount and isn’t possible once a payment is overdue |
| Platform risk | Errors, outages or Hive5 failing | A separate account for uninvested money; insolvency terms in the agreements | Delays, costs and possibly incomplete recovery |
| Country and regulatory risk | Laws change in Croatia or the lenders’ countries | Legal assessments of our current model | New rules can change how Hive5 or its lenders operate, as a Polish law in force from 2024 did for our Polish personal loans (Hive5 blog, 3 November 2023) |
| Concentration risk | Too much money in one lender, country or group | Several lenders, loan types and terms to choose from | All lenders belong to one group |
In practice, diversification can reduce concentration risk but can’t remove the risk of loss (help centre).
What independent reviewers and investors say
Independent reviews of Hive5 are mixed. We pay affiliates for referrals, so some reviews come from people we pay for sign-ups, while other sites earn fees from rival platforms. Check each site’s disclosure before you weigh its view.
The critics’ main points
Several independent review sites and investor blogs raise similar concerns:
- No financial services licence. That’s correct, and the licensing section above sets out our legal position and its limits.
- All lenders belong to one group. That’s also correct, and it’s the main reason to keep your Hive5 holding small and diversify beyond it.
- The buyback depends on that group. That’s right too, and the section above explains how the buyback works.
- Financial transparency. Some reviewers ask for more financial reporting. We publish the group’s audited accounts and our Transparency Hub, but we don’t publish default and recovery figures for each lender or the name of the bank that holds investor money.
Our response
Reviewers are right that Hive5 doesn’t operate under a financial services licence. However, our position rests on Croatian legal advice: a January 2024 opinion found we didn’t need a licence from the Croatian authorities at that time, and Babić & Partners advised in June 2026 that the model it reviewed doesn’t need an e-money licence. We publish summaries of that advice, not the full opinions.
We also publish Hive Finance Group’s audited 2024 consolidated accounts in full. The auditor, UAB “Veritas auditas”, gave an unmodified opinion on 10 April 2026 and drew attention to a material uncertainty about the group’s ability to continue as a going concern (note 22). Read that note before you invest. The 2024 accounts don’t cover every current lender, and we haven’t published 2025 accounts yet.
Under section 13 of the Investment Agreement, the company that sold you the claim owes the buyback, not us, and the agreements don’t describe a reserve fund or insurance behind it.
Finally, some older reviews say we have no secondary market. Our Secondary Market launched on 29 September 2026. You can sell a whole position with no overdue payments, at its outstanding principal or a discount of up to 50%, if another investor buys it. Hive5 charges no listing, purchase or sale fee there (User Agreement, section 7A).
What investors say on Trustpilot
On 11 November 2026 we had 506 reviews on Trustpilot and a TrustScore of 4.5; 68% were five-star and 4% one-star. We passed 500 reviews in October 2026. That said, we pay for a Trustpilot subscription and invite customers to leave reviews, and Trustpilot says it doesn’t fact-check them. In our early growth we also offered a €25 account credit for sharing a Trustpilot review, whatever the rating. We’ve since stopped, because we consider it was inappropriate.
Read how Hive5 works and manages risk
Investor stories
We also publish longer investor stories. Keep in mind that they describe personal experience, not typical results. Asked what she’d tell a friend, Ingrid, a Hive5 investor for about six months, said: “I would clearly tell him that this is a high-risk investment and that he should diversify across several platforms as much as possible.” (Translated from German; read Ingrid’s story.)
Pros and cons of Hive5
Hive5’s strengths are its low entry point, the buyback obligation under the Investment Agreement and its published legal assessments and accounts. Its weaknesses are the concentration in one group and the absence of the investor protection rules that come with licensed products.
| Pros | Cons |
|---|---|
| Start from €10, investing manually or with Auto Invest | Not covered by deposit guarantee or investor compensation schemes |
| A 60-day buyback obligation from the lending company under the Investment Agreement | The buyback depends on the lending company’s ability to pay |
| Published legal opinion (2024) and e-money advice (2026) | Hive5 doesn’t operate under a financial services licence |
| Uninvested money held separately from Hive5’s own funds | The separation doesn’t remove bank or insolvency risk |
| Option to offer investments for sale on the Secondary Market | A sale needs a buyer and may mean a discount |
| Public agreements and audited group accounts | Only three lenders, all in one group |
Who Hive5 may suit and who it may not
Hive5 may suit investors who understand loan-based investing, accept that they could lose money and want a small part of a diversified portfolio in consumer and business loans.
It’s probably not for you if you need your money back on a fixed date. The same goes if you want the cover of a deposit guarantee or investor compensation scheme. And if you’d rather not have a large share of your savings tied to one group of companies, keep any holding small or look elsewhere.
Before investing, our help centre suggests weighing your personal and family finances, your investment experience and knowledge, and how much risk you can take (help centre). In practice, that means asking yourself:
- Could you afford to lose the money you’d put in?
- Do you need it back by a fixed date?
- Are you comfortable that every lender belongs to one group?
- How much of your savings would sit with that one group?
If anything is unclear, talk to a qualified, independent adviser before investing.
How to check Hive5 for yourself
You can check most of this guide against public documents, so you don’t have to take our word for it.
- Look up our company. Enter 081441259 in the MBS field of the Croatian court register.
- Read our legal summaries. Start with the 2024 legal opinion post, the 2026 advice on the Transparency Hub and our July 2026 legal statement.
- Check the lending companies. Their details are on our loan originators page and their own websites (Credilink, Firmeo, FinJet).
- Read the group’s accounts. Download the group’s 2024 audited accounts, starting with the auditor’s report and note 22.
- Read the agreements. Go through the User Agreement and the Investment Agreement template, both in force since 28 September 2026, for late payments, the buyback and insolvency. All our current terms are on our legal documents page.
- Read the risk pages. See the risks and safeguards answers in our help centre.
- Read reviews at every star rating. Browse Trustpilot reviews at every star rating, and note which reviewers earn referral fees.
- Check warning lists. Search for warnings using I-SCAN or your national regulator, linked in the licensing section.
Frequently asked questions about Hive5
What is Hive5?
Hive5 is a loan investment marketplace. Hive5 marketplace d.o.o. in Zagreb, Croatia, runs it, and it’s part of Hive Finance Group. You buy claim rights on loans issued by the lending companies in our group, from €10. Hive5 does not operate under a financial services licence, and your capital is at risk.
Is Hive5 safe to invest in?
No investment on Hive5 is risk-free. Each claim carries a 60-day buyback obligation from the lending company under the Investment Agreement, which depends on that company’s ability to pay, and all the lending companies belong to one group. Hive5 can suit a small part of a diversified portfolio if you accept that you could lose some or all of your money.
Is Hive5 legit?
Hive5 marketplace d.o.o. (registration number 081441259), a registered Croatian company owned by Hive Finance Group, runs Hive5 and has operated since July 2022. We publish our agreements, summaries of our legal advice and the group’s audited accounts, and our help centre explains what Hive5 is. Still, being a registered company doesn’t remove investment risk, so read the risks above.
Is Hive5 a scam?
Here are the facts you can check. Hive5 marketplace d.o.o. is an active company in the Croatian court register. We also name our owners and managers, and we publish our agreements and the group’s audited 2024 accounts, including the auditor’s going-concern note. Whether a company is real and whether you should invest are separate questions, and the risks above apply either way.
Is Hive5 regulated?
Hive5 does not operate under a financial services licence. Based on our current legal assessment, made with our legal advisers in Croatia, our model doesn’t require authorisation as a crowdfunding service provider, investment firm, payment institution or e-money institution.
What happens if a borrower doesn’t pay?
If a payment is more than 60 days late, or insolvency proceedings start against the borrower, the company that sold you the claim must buy it back with up to 60 days of interest. But the buyback depends on the lending company’s ability to pay.
Has anyone lost money on Hive5?
We don’t publish default rates or buyback volumes for our current lending companies. So losses are possible whenever a lending company can’t pay a buyback.
Are Hive5’s accounts audited?
Hive Finance Group’s consolidated accounts are. UAB “Veritas auditas” audited the 2024 accounts and gave an unmodified opinion on 10 April 2026, with a material uncertainty about whether the group can continue as a going concern (note 22). However, the 2024 accounts don’t cover every current lender, and we haven’t published 2025 accounts yet.
Are Hive5 investments covered by a deposit guarantee scheme?
No. They aren’t bank deposits, and no deposit guarantee or investor compensation scheme covers them. Also, the buyback is a contractual obligation of the lending company, not a state-backed guarantee.
What happens to my investments if Hive5 goes bankrupt?
Your existing investments would continue under their agreements. We would give investors information on their transactions, stop concluding new Investment Agreements and return available funds as the agreements and the law allow. Even so, servicing and repayments could slow down, and you might not get all your money back.
Who owns Hive5?
Hive Finance UAB in Vilnius owns Hive5. Its main shareholder is co-founder Andrius Rupšys, Ruptela Group also holds shares, and we said in May 2026 that Group CEO Krisjanis Znotins was becoming a minority shareholder. The same group owns the lending companies whose loans you buy on Hive5.
How does Hive5 make money?
The lending companies pay us service fees for running the marketplace (Transparency Hub). Any fees for investors follow the Price List on our website, as the User Agreement sets out.
Can I get my money out early?
You can withdraw money you haven’t invested to a personal bank account you’ve deposited from, and it can take up to two working days to arrive. Invested money comes back as borrowers repay loans or through the buyback. You can also offer an investment for sale on our Secondary Market, but a sale needs a buyer, may need a discount and can’t go ahead once a payment is overdue.
How are returns taxed?
That depends on where you live, and we don’t give tax advice. We don’t withhold tax from your interest. Instead, you declare and pay any tax due in your country of tax residence (help centre). You can generate a tax statement for any period in your account settings.
Where can I read Hive5 reviews?
Customer reviews are on Trustpilot, where you can filter by any star rating. P2P review sites and investor blogs also publish independent reviews. Some earn referral fees, so check their disclosures.
Conclusion: would you recommend investing in Hive5?
If someone asked “Would you recommend investing in Hive5?”, the short answer is that it depends on your risk appetite and the kind of investment you’re looking for. Hive5 isn’t risk-free: the buyback depends on the lending company’s ability to pay, every lending company belongs to one group, and no deposit guarantee or investor compensation scheme covers your money.
If your main aim is to diversify your portfolio with loan investments that carry stated interest rates, and you can accept losing some or all of the money you put in, Hive5 can be one option for a small part of that portfolio, from €10. However, if you need certainty about your capital or a fixed date to get your money back, it’s probably not the right fit.
Whichever you decide, read the Investment Agreement and the risks above first, and speak to an independent adviser if you’re unsure.
Questions and complaints
Email our support team at support@hive5.com, or browse our help centre.
Capital at risk. Investing involves risk, and you can lose some or all of the money you invest. Hive5 investments aren’t bank deposits and aren’t covered by a deposit guarantee or investor compensation scheme. Past performance doesn’t indicate future results. This content isn’t investment, legal or tax advice.